


 SIGN UP FOR FREE NEWSLETTER
Image by Lisa Maree Williams/Getty
Australian mortgage holders have just been hit with a fifth interest rate rise this year, but financial markets are increasingly betting the Reserve Bank may finally be finished.
Despite the cash rate reaching an 18-year high of 4.85%, investors and the economics teams at all four major banks now believe the next move is more likely to be down than up.
It means the question for borrowers is now shifting from how much higher rates will go to when relief might finally arrive.
The details
Although not unexpected, the Reserve Bank of Australia’s decision to raise interest rates for a fifth time in 2026 was greeted with dismay.
The central bank lifted Australia’s cash rate by 25 basis points to 4.85% on Melbourne Cup Day, taking rates to their highest level in 18 years, as it attempts to control an inflation breakout.
With most banks and financial institutions passing on the 25-basis-point rise in full, Australians with an average sized $700,000 variable housing loan will now have to find an extra $100–$125 a month to cover their mortgage repayments.
Taking that same-sized loan, the cumulative rise across the five rate hikes so far this year is a jaw-dropping $530–$550 a month.
However, in the minutes after the rate decision was announced, the Australian dollar actually fell - the opposite of what usually happens when central banks raise rates.
A higher cash rate usually sees a flow of money into a currency, not a sell-off.
It turns out what money market traders were betting on was not the immediate rate decision in front of them - they’d already priced that in - but what might happen next.
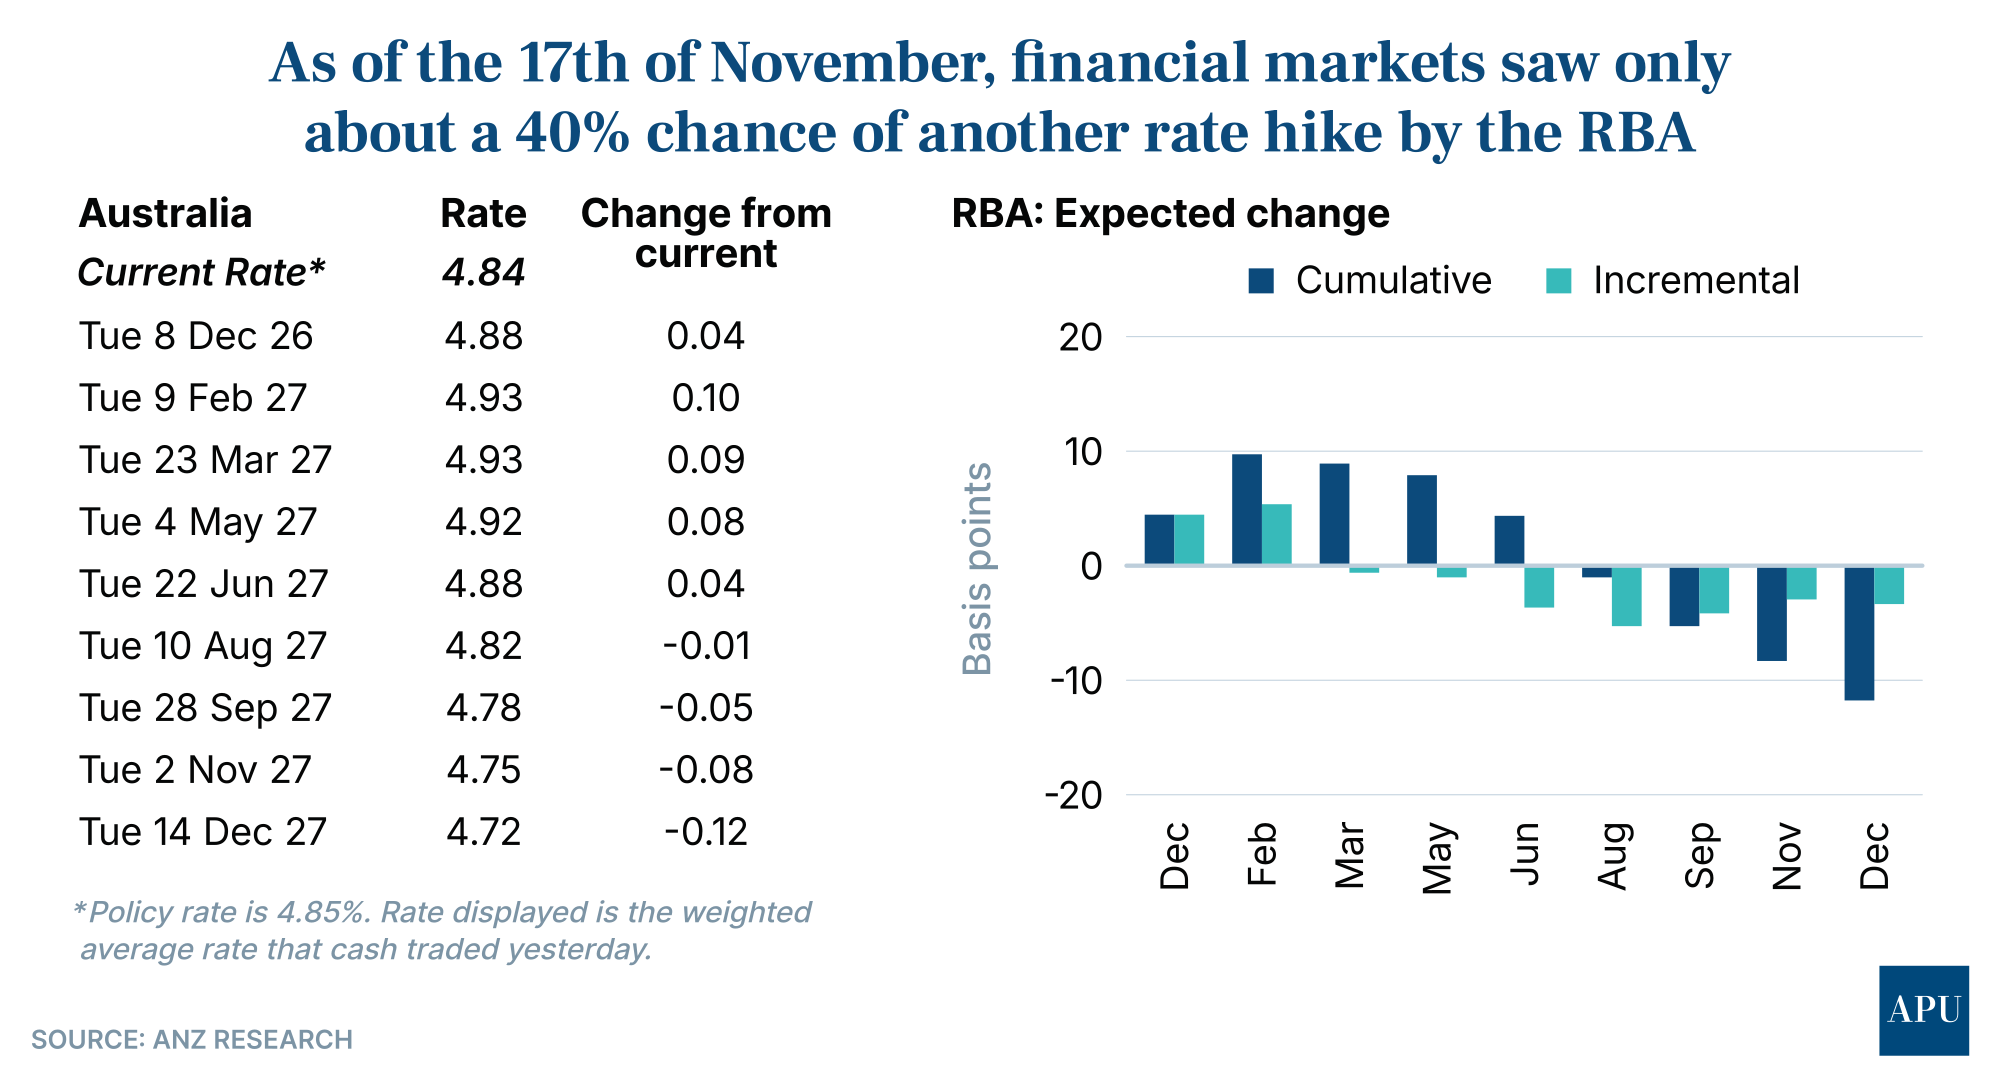
Two weeks later, financial markets were pricing nearly a 50% chance that the RBA’s next move would be an interest rate cut, possibly as early as August next year.
They’re not alone.
The economics teams at all of Australia’s big four banks believe the cash rate has peaked and the next move in interest rates is likely to be down.
None are predicting a rate rise at the RBA’s final Monetary Policy Board meeting for 2026 in December.
Belinda Allen, head of Australian economics at CBA, says there’s already compelling evidence of an economic slowdown, which will help bring inflation down.
“CBA card spend is slowing, the unemployment rate is rising and sentiment surveys are pessimistic,” she says.
“As a result, we see the RBA on hold in December and by the time of the February meeting, there should be enough evidence on growth and inflation that sees the RBA on hold.
“Rate cuts are in the cards for late in 2027 if enough progress has been made,” she says.
“We have these pencilled in for August and November. But a large degree of uncertainty remains on timing.
“It was already our view that the RBA was likely done hiking the cash rate after the November increase,” says Westpac’s chief economist Luci Ellis.
“Since then, our conviction on that call has strengthened.
“The housing market has undershot our forecasts over the past couple of months. We are also seeing early signs of a turn in the consumer.
“Business survey data has shown weaker conditions and a sharp decline in forward orders… oil and fuel prices are already materially lower than the track assumed in the RBA’s forecasts.”
ANZ’s Australian economics team agrees.
“In our view we are at, or close to, the cash rate peak and we are not forecasting another increase,” it says.
The language from the team at NAB is slightly more guarded.
“We think that the Board are now likely comfortable with the assessment that monetary policy is in restrictive territory. All else equal, this set up probably argues for a near-term pause. While we are not forecasting further policy tightening from here, there is little doubt the RBA will be sensitive (and responsive) to any upside surprise in inflation in coming months.”
The take-out
None of this means Australian mortgage holders should expect rapid relief from high interest rates.
The RBA has made it clear inflation remains too high, and another upside surprise in prices could still force it back into tightening mode.
But the balance of opinion has shifted significantly, with financial markets now pricing a much greater chance of cuts than further increases, while all four major banks believe the cash rate has either peaked or is very close to doing so.